Gratuity Calculator: Education Planning Checklist for Parents
A Gratuity Calculator can be useful for much more than estimating what you may receive when you leave a job in the UAE. For parents, it can also become a practical starting point for long-term education planning, especially when future school fees, university costs and relocation expenses are likely to require a large amount of money.
- How a Gratuity Calculator Works in the UAE
- UAE Gratuity Rules Parents Should Understand First
- Why Parents Can Use Gratuity as Part of an Education Plan
- Estimate Your Future Gratuity Before Estimating Education Costs
- Calculate Education Costs Separately From Gratuity
- Education Inflation Can Create a Large Future Funding Gap
- Use the Gratuity Calculator to Find Your Education Funding Gap
- Gratuity Should Usually Be a Backup, Not the Entire Education Strategy
- Keep Your Emergency Fund Separate From Education Savings
- Parents With More Than One Child Need Separate Calculations
- School Fees and University Fees Should Be Planned Separately
- Do Not Ignore the Basic Salary Structure in Your Employment Contract
- Update Your Gratuity Estimate After Salary Changes
- Do Not Treat an Online Gratuity Calculator as a Final Legal Entitlement
- A Practical Example of Using Gratuity for University Planning
- Common Mistakes Parents Make When Using a Gratuity Calculator
- Gratuity Calculator: Education Planning Checklist for Parents
Under the UAE Labour Law, end-of-service gratuity for eligible full-time employees in the private sector is generally calculated using the employee’s last basic salary, not the total salary package. For employees who complete more than one year of service, the standard formula is based on 21 days of basic wage for each year up to five years and 30 days for each additional year after that, subject to a maximum equivalent to 24 months’ wage.
That makes gratuity potentially valuable for families who spend many years working in the UAE. However, it should not be treated as a guaranteed education fund on its own. Employment changes, unpaid absences, salary structure, early resignation, legal deductions and future school-fee increases can all affect the amount available.
The smarter approach is to use a gratuity estimate as one part of a larger education plan. Calculate what you may receive, estimate what education could cost by the time your child reaches the relevant stage, identify the funding gap and then build savings or investments around that difference.
How a Gratuity Calculator Works in the UAE
A gratuity calculator estimates end-of-service benefits using information such as:
- Basic salary
- Length of service
- Employment type
- Start and end dates
- Applicable UAE Labour Law rules
The most important number is usually basic salary, because the UAE private-sector gratuity calculation is based on the employee’s last basic wage rather than the total monthly package.
That distinction matters because many UAE salary packages include separate allowances for housing, transport or other benefits.
For example, imagine an employee earns:
| Salary Component | Monthly Amount |
|---|---|
| Basic salary | AED 12,000 |
| Housing allowance | AED 5,000 |
| Transport allowance | AED 2,000 |
| Total salary | AED 19,000 |
For gratuity purposes, the relevant base would generally be the AED 12,000 basic salary rather than the full AED 19,000 package.
This is why parents should check their employment contract before using any online gratuity tool. Entering total salary instead of basic salary can create a much larger and misleading estimate.
UAE Gratuity Rules Parents Should Understand First
Before using a gratuity estimate for future education planning, it helps to understand the standard private-sector formula.
The UAE Labour Law provides that eligible full-time employees who complete more than one year of continuous service generally receive:
- 21 days of basic wage for each year of the first five years
- 30 days of basic wage for each additional year
- Total gratuity subject to a maximum of 24 months’ wage
Unpaid days of absence are not counted when calculating end-of-service gratuity.
A simplified example looks like this:
Employee details
- Basic salary: AED 10,000 per month
- Service: 8 years
Daily basic wage
AED 10,000 ÷ 30 = AED 333.33
First five years
21 days × AED 333.33 × 5 = approximately AED 35,000
Next three years
30 days × AED 333.33 × 3 = approximately AED 30,000
Estimated gratuity
Approximately AED 65,000
This is only a simplified illustration. Actual entitlements can depend on the employment arrangement, applicable law, deductions and whether the worker is covered by another approved end-of-service scheme.
Why Parents Can Use Gratuity as Part of an Education Plan
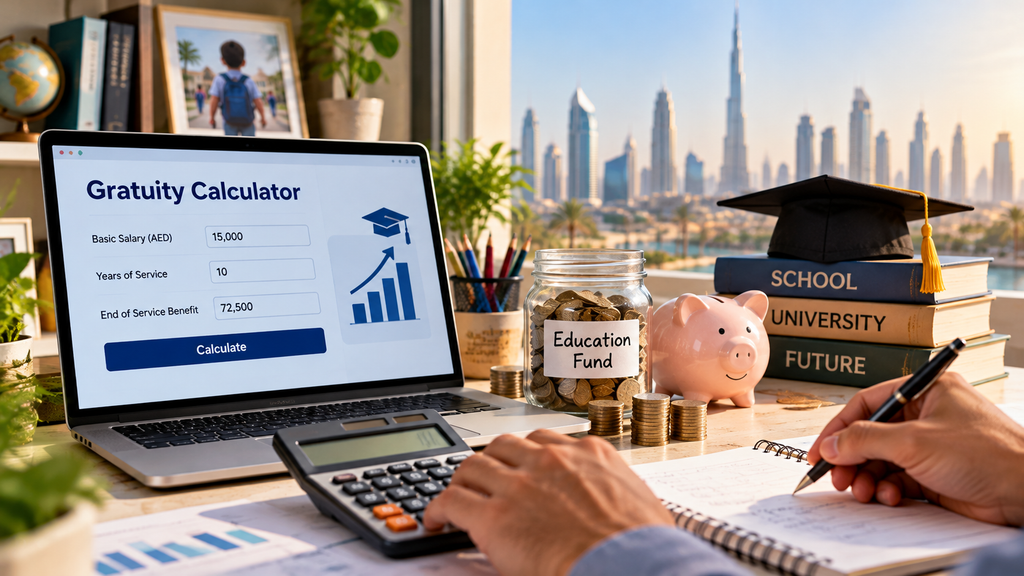
Education is one of the largest long-term costs many UAE families face.
School fees can already vary substantially across Dubai. Current KHDA school listings show examples ranging from below AED 10,000 a year at some schools to more than AED 60,000 at others, depending on curriculum and grade.
That difference becomes more important over time.
A child may spend:
- More than 10 years in school
- Several years in university
- Additional money on transport
- Books and devices
- Uniforms
- Activities
- Exams
- Accommodation if studying abroad
A gratuity payment received after a long period of UAE employment can therefore become a useful lump sum.
It might help cover:
- Final years of school
- University tuition deposit
- First-year university fees
- Overseas relocation costs
- Accommodation
- Education loan reduction
However, parents should avoid depending on gratuity as the only source of funding.
A stronger strategy is to treat gratuity as a future top-up amount, while building separate education savings over time.
Estimate Your Future Gratuity Before Estimating Education Costs
Education planning becomes easier when the numbers are separated into two sides.
The first side is the money you may have.
The second is the money you may need.
Start with the gratuity estimate.
A simple planning table could look like this:
| Item | Example |
|---|---|
| Current basic salary | AED 15,000 |
| Current completed service | 6 years |
| Expected total service | 12 years |
| Estimated future gratuity | Calculate using applicable formula |
| Current education savings | AED 80,000 |
| Expected additional savings | AED 150,000 |
| Total potential education fund | Gratuity + savings |
This gives parents a much clearer picture than simply saying, “My gratuity should cover university.”
The estimate should also be updated when:
- Basic salary changes
- Employment changes
- Child moves to a different school
- University plans change
- Currency assumptions change
An annual review is usually enough for long-term planning.
Calculate Education Costs Separately From Gratuity
The next step is to estimate what education may actually cost.
Do not compare gratuity only with today’s tuition fees.
If your child is five years old and university starts at 18, the relevant cost is the likely fee 13 years from now, not the current fee.
Your education budget should include more than tuition.
| Education Cost | Include in Your Plan? |
|---|---|
| School tuition | Yes |
| Transport | Yes |
| Books and devices | Yes |
| Uniforms | Yes |
| Exam charges | Yes |
| Extracurricular activities | If relevant |
| University tuition | Yes |
| Accommodation | If studying away from home |
| Flights | If studying overseas |
| Visa and insurance | If applicable |
KHDA fact sheets show why this matters. School charges can extend beyond tuition to optional or additional services, and fee structures can differ substantially between schools.
Parents should therefore build a complete annual education cost rather than using one headline tuition figure.
Education Inflation Can Create a Large Future Funding Gap
One of the easiest mistakes is assuming fees will remain at today’s level.
Dubai’s private-school fees are regulated through KHDA’s fee framework, and eligible fee movements have historically been linked to factors such as the Educational Cost Index and school performance.
Even when fees are stable for a particular year, long-term planning should allow for future increases.
Consider this simple illustration.
Suppose current annual school fees are AED 40,000.
If you use an assumed education-cost increase of 4% annually for planning purposes:
| Time From Now | Estimated Annual Fee |
|---|---|
| Today | AED 40,000 |
| 5 years | About AED 48,700 |
| 10 years | About AED 59,200 |
| 15 years | About AED 72,000 |
These are only planning assumptions, not predictions of actual KHDA-approved increases.
The purpose is to show how even moderate annual increases can materially change a family’s funding requirement over a long period.
Parents should therefore use conservative assumptions and review them periodically rather than relying on one estimate for the next 15 years.
Use the Gratuity Calculator to Find Your Education Funding Gap
Once you have estimated both gratuity and future education costs, calculate the gap.
The basic formula is:
Future education cost − existing savings − expected gratuity = funding gap
For example:
| Planning Item | Amount |
|---|---|
| Estimated future university cost | AED 500,000 |
| Existing education savings | AED 120,000 |
| Expected future gratuity | AED 180,000 |
| Remaining funding gap | AED 200,000 |
The family does not need to find AED 500,000 from scratch.
It needs to build approximately AED 200,000 more, based on these assumptions.
That makes the goal much easier to understand.
The next step is to calculate how much needs to be saved each month or year to close the gap before the child reaches university age.
Gratuity Should Usually Be a Backup, Not the Entire Education Strategy
Using gratuity in education planning does not mean waiting until employment ends before saving anything.
That creates unnecessary risk.
Several things can change over a long career:
- You may leave the UAE earlier
- Your basic salary may change
- Your employer may change
- Your child may choose a more expensive university
- Currency exchange rates may move
- Education inflation may exceed expectations
Parents should therefore build education savings independently.
Gratuity can then strengthen the plan later.
A useful way to think about the fund is:
| Funding Source | Role |
|---|---|
| Monthly savings | Core education fund |
| Investments | Potential long-term growth |
| Employer education allowance | Reduces current costs |
| Scholarships | Potential future reduction |
| Gratuity | Long-term top-up |
| Emergency fund | Should remain separate |
This structure reduces the risk of one source failing to meet the entire cost.
Keep Your Emergency Fund Separate From Education Savings
Parents sometimes count every available dirham toward school or university.
That can create a different financial problem.
Your emergency fund should normally remain separate because unexpected events can happen before your child reaches university.
These may include:
- Job loss
- Medical expenses
- Relocation
- Family emergencies
- Temporary income reduction
If education savings also serve as the emergency fund, a single crisis may destroy years of education planning.
A better system uses separate financial buckets.
Emergency fund protects the family now.
Education fund supports the child later.
Gratuity may strengthen long-term plans when employment ends.
Keeping these purposes separate creates more realistic financial planning.
Parents With More Than One Child Need Separate Calculations
Education planning becomes much more complicated when there are two or three children.
Do not simply multiply the first child’s expected cost without considering timing.
For example:
| Child | University Starts | Estimated Funding Need |
|---|---|---|
| Child 1 | 2032 | AED 350,000 |
| Child 2 | 2036 | AED 410,000 |
| Child 3 | 2040 | AED 475,000 |
The expenses occur at different times.
That matters because gratuity may be available only once, while education bills can continue for many years.
Parents should therefore decide in advance how gratuity will be allocated.
One approach could be:
- Gratuity covers part of Child 1’s university
- Existing investments cover Child 2
- Monthly savings continue toward Child 3
Another family may decide to divide the gratuity equally between children.
There is no universal correct method, but making the decision early prevents one child’s education from accidentally consuming the full amount.
School Fees and University Fees Should Be Planned Separately
School and university costs create different financial pressures.
School fees are recurring annual expenses paid while parents are still earning.
University costs can be much larger and may arrive after the child turns 18, potentially around the same period when parents are thinking about retirement.
That means it is useful to separate them.
School fund
Designed for near- and medium-term costs.
University fund
Designed for a larger long-term target.
Gratuity allocation
Can be reserved primarily for university if current income already covers school.
This approach may be especially useful for UAE expatriate families.
If parents can comfortably pay annual school fees from salary, preserving gratuity for higher education may provide more value than using it on routine school expenses.
Do Not Ignore the Basic Salary Structure in Your Employment Contract
A common planning mistake is assuming future gratuity will grow at the same rate as total salary.
That may not happen.
Because gratuity is generally calculated using basic wage, the relationship between basic salary and total compensation matters.
Consider two employees:
| Employee | Total Salary | Basic Salary |
|---|---|---|
| Employee A | AED 25,000 | AED 18,000 |
| Employee B | AED 25,000 | AED 10,000 |
Both receive the same total monthly package.
Their potential gratuity calculations could still be very different because Employee A has the higher basic salary.
Parents planning around future gratuity should therefore review the salary breakdown, not simply their bank credit each month.
Update Your Gratuity Estimate After Salary Changes
If your basic salary increases, your expected end-of-service benefit may change significantly because the calculation is based on the last due basic wage under the standard rules.
This means long-serving employees should revisit the calculation after:
- Promotion
- Salary restructuring
- Employer change
- Contract amendment
Suppose your original education plan assumed a basic salary of AED 10,000.
Five years later, your basic salary becomes AED 18,000.
Your expected gratuity may now play a much larger role in the future education fund.
The reverse can also happen if you move to a job with a lower basic salary or become covered under a different employment arrangement.
Keep the estimate current rather than relying on a number calculated years ago.
Do Not Treat an Online Gratuity Calculator as a Final Legal Entitlement
A calculator is useful for planning, but it is still an estimate.
Actual end-of-service benefits can be affected by the exact terms of employment, applicable UAE legislation, unpaid absence, lawful deductions and alternative end-of-service arrangements.
The UAE Labour Law also allows eligible deductions or amounts due to the employer to be taken from gratuity in certain circumstances.
That means your education plan should include some margin for error.
For example, if a calculator estimates AED 200,000, you might choose to build your plan around a more conservative figure such as AED 170,000 or AED 180,000 until the actual benefit becomes payable.
Conservative assumptions make the plan more resilient.
A Practical Example of Using Gratuity for University Planning
Consider a UAE parent with the following situation:
- Child’s current age: 8
- University starts in: 10 years
- Current basic salary: AED 16,000
- Expected UAE service at exit: 15 years
- Existing education savings: AED 100,000
A simplified gratuity estimate would use the standard formula of 21 days per year for the first five years and 30 days per year after that.
Daily basic salary
AED 16,000 ÷ 30 = AED 533.33
First five years
AED 533.33 × 21 × 5 = approximately AED 56,000
Next 10 years
AED 533.33 × 30 × 10 = approximately AED 160,000
Estimated gratuity
Approximately AED 216,000
Now assume the family estimates future university costs at AED 500,000.
| Funding Source | Amount |
|---|---|
| Current education savings | AED 100,000 |
| Estimated gratuity | AED 216,000 |
| Total identified funds | AED 316,000 |
| Estimated university cost | AED 500,000 |
| Remaining gap | AED 184,000 |
Instead of wondering how to save AED 500,000, the family can now focus on building the remaining AED 184,000 over the next 10 years.
That is the real value of using a gratuity calculator in education planning.
Common Mistakes Parents Make When Using a Gratuity Calculator
One common mistake is entering total salary instead of basic salary.
This can dramatically overstate the expected payout.
Another mistake is assuming today’s gratuity estimate will remain accurate for the next decade. Employment conditions and salary can change.
Parents also sometimes compare today’s school or university fee with a gratuity amount they will receive many years later without allowing for education inflation.
Another issue is double-counting money.
For example, a parent may include gratuity in the education fund while also assuming the same gratuity will fund retirement or a property purchase.
One future payment cannot finance several major goals simultaneously.
Finally, families sometimes forget that gratuity is normally received when employment ends.
If university fees become due while the parent is still working for the employer, the gratuity may not yet be available.
Gratuity Calculator: Education Planning Checklist for Parents
A simple annual review can keep the plan realistic.
| Planning Question | Check |
|---|---|
| What is my current basic salary? | Confirm from contract or payroll |
| How many years have I completed? | Update service period |
| What is my estimated gratuity? | Recalculate |
| Has my child’s school fee changed? | Update annual costs |
| What is the future university estimate? | Review target |
| Have I allowed for inflation? | Use a reasonable planning assumption |
| How much have I already saved? | Update balance |
| What is the remaining funding gap? | Recalculate |
| Am I using gratuity for another goal? | Avoid double-counting |
| Is my emergency fund separate? | Keep separate |
| Has my job or contract changed? | Adjust assumptions |
Using a Gratuity Calculator this way turns it from a simple employment-benefit tool into a broader financial-planning tool.
The UAE’s standard private-sector gratuity rules provide a clear starting point: eligible employees generally receive 21 days of basic wage for each of the first five years and 30 days for each additional year, with the calculation based on the last basic salary and the overall benefit subject to the statutory cap.
At the same time, education costs can vary enormously. Current KHDA school information shows annual fees ranging from relatively affordable levels to more than AED 60,000 at individual Dubai schools, before additional expenses are considered.
The strongest plan therefore uses both numbers carefully.
Estimate gratuity.
Estimate future education costs.
Allow for inflation.
Subtract existing savings.
Then calculate the gap that still needs to be funded.
Gratuity can become a valuable contribution toward your child’s future education, but it works best when it supports a disciplined savings strategy rather than replacing one.
Do follow us on Instagram
Read More – Building Materials List: A Practical Guide for Construction Projects