Money Habits: How Can Smart Financial Choices Help You Build a Better Future?
Money habits are the everyday decisions and routines that influence how people earn, spend, save, borrow, and invest their money. These habits may seem small, but over time, they can have a significant impact on financial stability and quality of life. From preparing a monthly budget to avoiding unnecessary purchases, every financial decision contributes to a person’s overall relationship with money.
- How Can You Develop Good Money Habits?
- Why Is Budgeting One of the Most Important Money Habits?
- How Can Saving Money Regularly Improve Your Financial Future?
- What Is an Emergency Fund, and How Can You Build One?
- How Can You Control Spending Without Giving Up Everything You Enjoy?
- Why Should You Track Your Daily Expenses?
- How Can You Avoid Impulse Buying and Unnecessary Purchases?
- How Can Good Money Habits Help You Manage Debt?
- What Are the Best Money Habits for Young Adults and Students?
- How Can Families Develop Better Household Money Habits?
- How Can You Make Your Money Work for You?
- How Can You Improve Your Financial Discipline?
- What Money Habits Should You Avoid?
- How Can You Build a Monthly Money Management Routine?
- Can Small Money Habits Really Make a Big Difference Over Time?
Developing good money habits is not only about becoming wealthy. It is also about reducing financial stress, preparing for unexpected expenses, meeting personal goals, and gaining greater control over everyday life. People who understand their spending patterns are often better positioned to make informed choices and avoid financial difficulties caused by overspending or excessive debt.
For example, setting aside a small amount of money every month can gradually build an emergency fund. Similarly, reviewing expenses regularly can help identify unnecessary subscriptions, frequent impulse purchases, and other costs that may be reduced. These simple practices demonstrate how consistent financial discipline can support long-term financial well-being.
Whether someone is a student, a working professional, a business owner, or a family managing household expenses, healthy money habits can provide a practical foundation for a more secure financial future.
How Can You Develop Good Money Habits?
Developing good money habits begins with understanding your current financial situation and identifying the changes that could improve it. Instead of attempting to transform every financial behavior at once, it is generally more practical to introduce small, manageable routines and maintain them consistently.
The first step is to understand how much money comes in, how much goes out, and what financial responsibilities need attention. Once these details are clear, it becomes easier to decide how much to spend on necessities, how much to save, and how to work towards future goals.
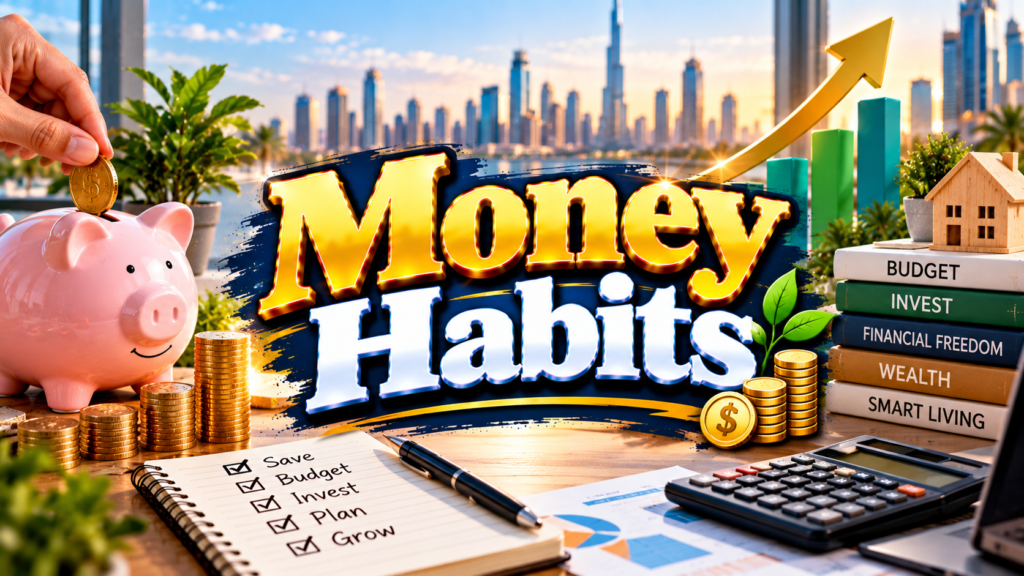
Some useful habits to develop include:
- Tracking daily expenses to understand spending patterns.
- Preparing a realistic monthly budget.
- Saving a portion of income regularly.
- Paying bills and debt instalments on time.
- Comparing prices before making major purchases.
- Building an emergency fund for unexpected costs.
- Reviewing financial goals every month.
- Learning the basics of saving, investing, and borrowing.
Consistency is more important than perfection. Missing a savings target occasionally does not mean a financial plan has failed. The important thing is to understand why it happened, adjust the budget if necessary, and continue working towards the goal.
Why Is Budgeting One of the Most Important Money Habits?
Budgeting is one of the most effective ways to understand and manage personal finances. A budget is a plan that shows how available income will be allocated to essential expenses, savings, debt repayments, and discretionary spending. It helps people make intentional financial decisions instead of relying on guesswork.
Without a budget, it can be difficult to understand why money disappears before the end of the month. Small expenses, online purchases, food deliveries, subscriptions, and transportation costs may seem insignificant individually but can become substantial when combined.
Creating a monthly budget does not necessarily require complicated software or financial expertise. A notebook, spreadsheet, or budgeting application can help organise income and expenses.
A simple budgeting process includes:
- Calculate your monthly take-home income.
- List fixed expenses such as rent, loan repayments, and insurance.
- Estimate variable expenses such as groceries, utilities, and transport.
- Decide how much you can reasonably save.
- Allocate money for discretionary spending.
- Review actual expenses at the end of the month.
One popular approach is the 50/30/20 budgeting rule, which suggests allocating approximately 50% of after-tax income to needs, 30% to wants, and 20% to savings and debt repayment. However, these percentages are only a guideline. Housing costs, family responsibilities, income levels, and debt obligations may require a different arrangement.
The best budget is one that reflects your real circumstances and helps you make steady progress without creating unrealistic expectations.
How Can Saving Money Regularly Improve Your Financial Future?
Saving money regularly is a valuable financial habit because it creates a reserve for future needs and unexpected events. Even modest contributions can become meaningful when maintained over time. Regular saving also encourages people to distinguish between what they can afford today and what they may need tomorrow.
Many people wait until the end of the month to save whatever remains. Unfortunately, unexpected expenses and discretionary purchases can leave little money available. A more structured approach is to set a savings target when income arrives and transfer the intended amount into a separate savings account.
For example, someone who saves ₹2,000 each month will contribute ₹24,000 over one year, excluding interest or investment returns. This illustrates how consistent contributions can accumulate even when the monthly amount is relatively small.
To make saving easier:
- Set a specific purpose for each savings goal.
- Automate transfers where practical.
- Start with an affordable amount and increase it when possible.
- Keep emergency savings accessible.
- Review savings progress regularly.
- Avoid withdrawing money for non-essential purchases.
Savings goals may include education, home improvements, travel, healthcare expenses, retirement, or a future business. Giving each goal a clear purpose can make saving more motivating and easier to maintain.
What Is an Emergency Fund, and How Can You Build One?
An emergency fund is money reserved for unexpected expenses or financial disruptions. These may include medical bills, urgent home repairs, essential vehicle repairs, or a temporary loss of income. Having accessible savings can reduce the need to borrow money when an unforeseen expense occurs.
A common guideline is to aim for three to six months of essential living expenses. However, the appropriate amount depends on individual circumstances. People with irregular incomes, dependants, or less predictable employment may prefer a larger reserve, while those starting from scratch can build towards a smaller initial target.
Building an emergency fund can begin with a modest goal. Saving enough to cover one unexpected bill may be a useful first milestone. Once that amount is established, contributions can gradually increase.
Consider the following steps:
- Estimate essential monthly expenses.
- Choose an initial savings target.
- Open or designate an account for emergency savings.
- Contribute regularly according to your budget.
- Replenish the fund after using it for a genuine emergency.
Emergency savings should generally be kept somewhere accessible and relatively low-risk rather than in highly volatile investments. The purpose is to provide financial protection when needed, not to maximise investment returns.
How Can You Control Spending Without Giving Up Everything You Enjoy?
Controlling spending does not mean eliminating every enjoyable activity. It means understanding which purchases provide genuine value and which expenses interfere with important financial priorities.
A healthy spending habit allows room for entertainment, hobbies, occasional treats, and social activities while keeping essential expenses and savings on track. The objective is to make deliberate choices rather than spending automatically.
One useful strategy is to distinguish between needs and wants. Needs include essential food, housing, utilities, healthcare, and necessary transportation. Wants include many discretionary purchases, such as upgrading a functioning device, buying extra clothing, or ordering food for convenience.
Before making a non-essential purchase, ask yourself:
- Do I genuinely need this item?
- Will I use it regularly?
- Does it fit within my budget?
- Am I buying it because I feel stressed or bored?
- Could I achieve the same result at a lower cost?
Another useful method is the waiting rule. For example, wait 24 hours before making a small, non-urgent purchase or several days before buying something expensive. This pause can help separate a genuine preference from a temporary impulse.
You can also set a monthly allowance for discretionary spending. Once that amount is used, postpone additional purchases until the next budgeting period. This approach provides flexibility while preventing spending from expanding without limits.
Why Should You Track Your Daily Expenses?
Expense tracking helps reveal where money is actually going. Many people remember major purchases but overlook smaller, repeated payments that gradually affect their monthly budget.
Recording expenses does not need to be complicated. You can use a mobile application, spreadsheet, notebook, or banking transaction history. The important thing is to record purchases consistently and review them regularly.
Organise spending into categories such as:
- Housing and household bills.
- Groceries and dining.
- Transportation.
- Healthcare and personal care.
- Entertainment and shopping.
- Debt repayments.
- Savings and investments.
After tracking expenses for several weeks, look for patterns. You may discover that convenience purchases, unused subscriptions, or frequent small transactions account for more spending than expected.
The purpose of tracking is not to feel guilty about every purchase. Instead, it is to identify opportunities to redirect money towards more meaningful priorities. Even reducing a few unnecessary expenses can create additional room for savings or debt repayment.
How Can You Avoid Impulse Buying and Unnecessary Purchases?
Impulse buying occurs when someone makes a purchase without carefully considering whether it is necessary, affordable, or aligned with their goals. Online shopping platforms, promotional emails, limited-time offers, and social media advertising can make spontaneous purchases especially tempting.
One effective way to reduce impulse buying is to prepare a shopping list before visiting a store or browsing online. This establishes a clear purpose and makes it easier to avoid unrelated products.
Other helpful strategies include:
- Remove saved payment details from shopping websites if they encourage spontaneous purchases.
- Unsubscribe from promotional messages that trigger unnecessary spending.
- Compare prices before buying expensive items.
- Avoid shopping when feeling bored, upset, or under pressure.
- Check whether an item can be borrowed, repaired, or purchased second-hand.
- Review return policies and total costs before completing an order.
It is also useful to calculate the full cost of ownership. A product may have an attractive purchase price but require maintenance, accessories, subscriptions, or replacement parts.
Learning to pause before purchasing can gradually improve financial discipline. The goal is not to avoid every sale or bargain but to buy things that genuinely support your needs and priorities.
How Can Good Money Habits Help You Manage Debt?
Debt can become difficult to manage when repayments consume too much of a person’s income. Developing responsible borrowing and repayment habits can help reduce financial pressure and make progress towards financial goals.
The first step is to list all outstanding debts, including their balances, interest rates, minimum payments, and due dates. This overview helps clarify the total obligation and identify which debts may be most expensive.
Two common repayment strategies are the debt avalanche and debt snowball methods.
Debt avalanche method: Make the required minimum payments on all debts and direct additional repayment money towards the debt with the highest interest rate. This approach can reduce total interest costs when other factors are equal.
Debt snowball method: Make minimum payments on all debts and focus additional money on the smallest balance first. Paying off smaller debts can provide a sense of progress and motivation.
Both approaches can be useful, depending on a person’s financial circumstances and preferences. Essential expenses and minimum contractual payments should remain priorities.
Good debt habits also include paying bills on time, reviewing loan terms before borrowing, avoiding unnecessary high-interest debt, and understanding the consequences of missed payments. If repayments become unmanageable, contacting the lender early or seeking qualified financial counselling may help identify available options.
What Are the Best Money Habits for Young Adults and Students?
Young adulthood is an important time to establish financial routines. Students and young professionals may be managing their own income and expenses for the first time, making it a valuable opportunity to develop practical skills.
The most useful habits are often simple rather than complicated. Learning to budget, save regularly, understand bank fees, and distinguish between essential spending and discretionary purchases can provide a strong foundation.
Young adults can benefit from the following practices:
- Prepare a monthly budget based on actual income.
- Build an initial emergency fund.
- Understand the terms of student loans and other borrowing.
- Avoid taking on debt to maintain an unrealistic lifestyle.
- Learn about interest, inflation, and the effects of compounding.
- Review financial products carefully before opening accounts.
- Set goals for education, career development, and future expenses.
It is also important to be cautious about financial advice found on social media. Promises of guaranteed returns, effortless wealth, or quick profits may conceal substantial risks or scams.
Starting with basic financial education can help young people make informed decisions as their incomes, responsibilities, and goals change.
How Can Families Develop Better Household Money Habits?
Household finances often involve balancing several priorities, including housing, groceries, education, healthcare, transportation, savings, and family activities. A clear financial plan can help households allocate resources more effectively.
Families can begin by preparing a shared overview of income, regular expenses, outstanding debts, and savings goals. This encourages transparency and helps household members understand the financial commitments that affect everyone.
Practical household money habits include planning meals before grocery shopping, comparing utility plans where appropriate, reviewing recurring subscriptions, and setting aside money for predictable annual expenses.
It can also be helpful to create separate savings targets for different purposes, such as education, home repairs, holidays, and emergencies. These categories make it easier to understand how available money is being allocated.
Regular financial discussions can prevent misunderstandings and encourage shared responsibility. For households with children, age-appropriate conversations about saving, spending, and needs versus wants can introduce useful financial concepts early.
The most effective household financial system is one that reflects the family’s income, responsibilities, and priorities rather than following a rigid formula.
How Can You Make Your Money Work for You?
Making money work for you involves using financial resources thoughtfully to support present needs and future goals. This may include maintaining savings, paying down expensive debt, investing for long-term objectives, and developing skills that improve earning potential.
Saving and investing serve different purposes. Savings generally provide greater accessibility and stability, making them useful for short-term goals and emergencies. Investments may offer opportunities for long-term growth but can fluctuate in value and involve the risk of losing money.
Before investing, consider your financial goals, time horizon, risk tolerance, existing debt, and need for accessible cash. Understand the product, fees, tax implications, and potential losses before committing money.
Diversification, which involves spreading investments across different assets, can help reduce dependence on any single investment, although it cannot eliminate market risk.
It is also worth understanding compound growth. Compounding occurs when returns are earned on previous returns as well as on the original amount invested. Over long periods, this effect can contribute significantly to growth, but actual results depend on investment performance, costs, taxes, and other factors.
There is no single financial product that is appropriate for everyone. A balanced financial plan should reflect personal circumstances and realistic expectations rather than promises of rapid wealth.
How Can You Improve Your Financial Discipline?
Financial discipline is the ability to follow a financial plan even when immediate temptations or unexpected circumstances make it difficult. It is not about being perfect or denying yourself every pleasure. It is about consistently making choices that support your priorities.
One practical approach is to create routines around payday, bill payments, savings transfers, and monthly reviews. When these activities become part of a regular schedule, they require less decision-making effort.
You can strengthen financial discipline by setting specific and measurable goals. Instead of saying, “I want to save more money,” choose a target that fits your circumstances, such as saving a manageable amount each month for a defined purpose.
Accountability can also help. Some people prefer reviewing their progress independently, while others benefit from discussing shared goals with a trusted family member or partner.
When a financial mistake occurs, treat it as information rather than a permanent failure. Review what happened, adjust the plan, and identify one practical change that can prevent the same problem in the future.
Over time, small and repeatable decisions can become reliable habits that support better financial outcomes.
What Money Habits Should You Avoid?
Some financial behaviors can gradually weaken financial stability, even when income appears sufficient. Recognizing these patterns is an important part of improving money management.
Common habits to reconsider include:
- Spending more than you earn over extended periods.
- Ignoring bank statements and outstanding bills.
- Relying on high-interest borrowing for routine expenses.
- Delaying savings indefinitely.
- Making purchases solely to impress others.
- Investing in products you do not understand.
- Ignoring fees, interest rates, and loan conditions.
- Depending on unverified financial advice.
- Failing to prepare for predictable annual expenses.
Another common mistake is lifestyle inflation, which occurs when spending rises as income increases. Higher earnings can improve quality of life, but allowing every increase in income to become a new expense may prevent savings from growing.
A useful response is to decide in advance how additional income will be divided between essential needs, personal enjoyment, debt repayment, and long-term goals.
Avoiding these behaviours does not guarantee wealth, but it can reduce preventable financial problems and make it easier to respond to changing circumstances.
How Can You Build a Monthly Money Management Routine?
A monthly financial routine can turn good intentions into practical action. Rather than reviewing finances only when a problem occurs, set aside a short period each month to evaluate progress and make adjustments.
At the beginning of the month, review expected income, upcoming bills, savings targets, and planned purchases. During the month, track expenses and check whether spending remains within the budget.
At the end of the month, ask yourself a few questions:
- Did I cover my essential expenses?
- Did I meet my savings target?
- Were there any unexpected costs?
- Did I spend more than planned in any category?
- Do I need to adjust my budget for next month?
- Am I making progress towards my longer-term goals?
You can also review subscriptions, bank fees, debt balances, and upcoming annual payments.
A monthly review should be practical and encouraging. It is an opportunity to identify what worked, recognise improvements, and address problems before they become more serious.
If income varies from month to month, consider preparing your budget around a conservative estimate of income and prioritising essential expenses. During higher-income months, additional money may be allocated to savings, debt reduction, or other established goals.
Can Small Money Habits Really Make a Big Difference Over Time?
Yes, small money habits can make a meaningful difference because their effects may accumulate over months and years. Regular saving, careful spending, timely debt repayments, and thoughtful financial planning can help create more options and reduce avoidable financial pressure.
For example, reviewing recurring expenses may free up money for an emergency fund. Avoiding unnecessary borrowing can reduce interest costs. Learning about investment risks can help prevent decisions based on unrealistic promises. These actions may not produce immediate dramatic results, but they can support a more resilient financial position over time.
The outcome depends on several factors, including income, living costs, family responsibilities, economic conditions, and unexpected events. Good financial habits cannot eliminate every difficulty, and some people may have limited room to save despite careful budgeting.
Nevertheless, developing a clear understanding of your finances can help you make better-informed decisions with the resources available to you.
Conclusion: How Can You Start Building Better Money Habits Today?
Building better money habits begins with small, consistent actions rather than dramatic financial changes. Understanding your spending, preparing a realistic budget, saving regularly, managing debt responsibly, and planning for unexpected expenses can all contribute to stronger financial foundations.
The most effective approach is to choose a few habits that are practical for your current situation and build on them gradually. Start by tracking expenses, setting one achievable savings goal, or reviewing your monthly bills. Once these routines become familiar, introduce additional improvements.
Remember that financial progress looks different for everyone. Your goals may involve reducing debt, building emergency savings, supporting your family, purchasing a home, or preparing for retirement. What matters is having a realistic plan and reviewing it as your circumstances change.
Healthy money habits are not about becoming wealthy overnight. They are about making thoughtful decisions repeatedly, learning from experience, and creating greater financial flexibility for the future. By starting today and remaining consistent, you can develop a more confident and organized approach to managing your money.
Disclaimer: This article is for general educational purposes only and does not constitute personalized financial, investment, tax, or legal advice. Consider consulting a qualified professional for guidance based on your individual circumstances.
Do follow us on Instagram
Read More – UAE Personal Finance Guide